
Expert analysis
Gas prices are correcting, but winter supply risks and geopolitical tensions in the Middle East continue to pose upside price risks.
On Monday, TTF fell to its lowest level since mid-Oct (FM contract at around EUR 83/MWh), while European gas storage levels remain historically low and uncertainty surrounding the Strait of Hormuz persists.
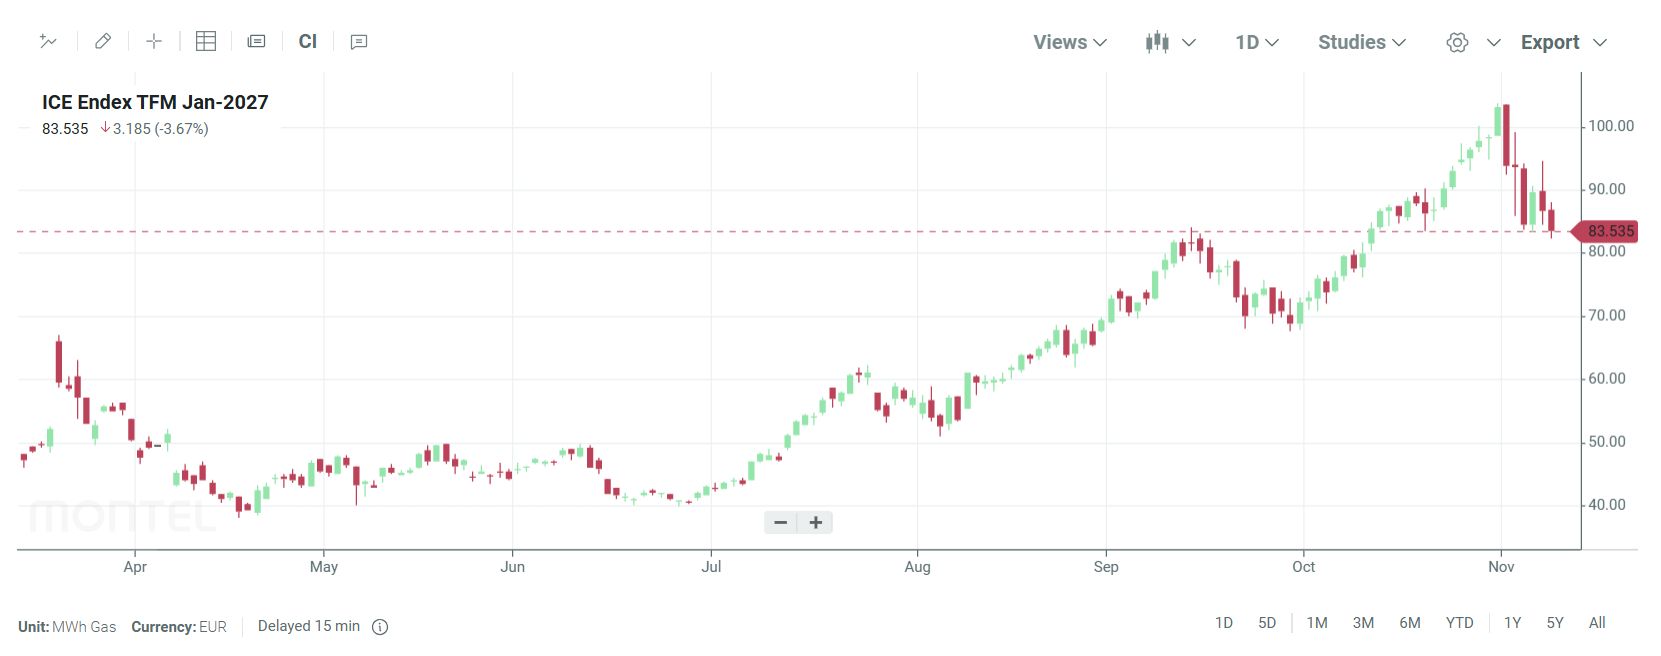
Gas market – Falling oil prices weigh on TTF, but winter fundamentals could limit further downside
The TTF FM contract fell to an intraday low of EUR 82.30/MWh on Monday, its lowest level since 12 October and approximately 21% below the nearly four-year high of EUR 104.36/MWh recorded on 30 Oct.
The correction has been largely driven by falling oil prices, with Brent declining to USD 96.68/bbl. Market participants note that short-term TTF price movements remain closely correlated with developments in the oil market.
Despite the price decline, European gas storage facilities are only 73% full, while withdrawals are gaining momentum. The storage withdrawal season started earlier than in previous years, while low French hydropower reserves and uncertainty surrounding weather conditions in January and February add further pressure to the supply outlook.
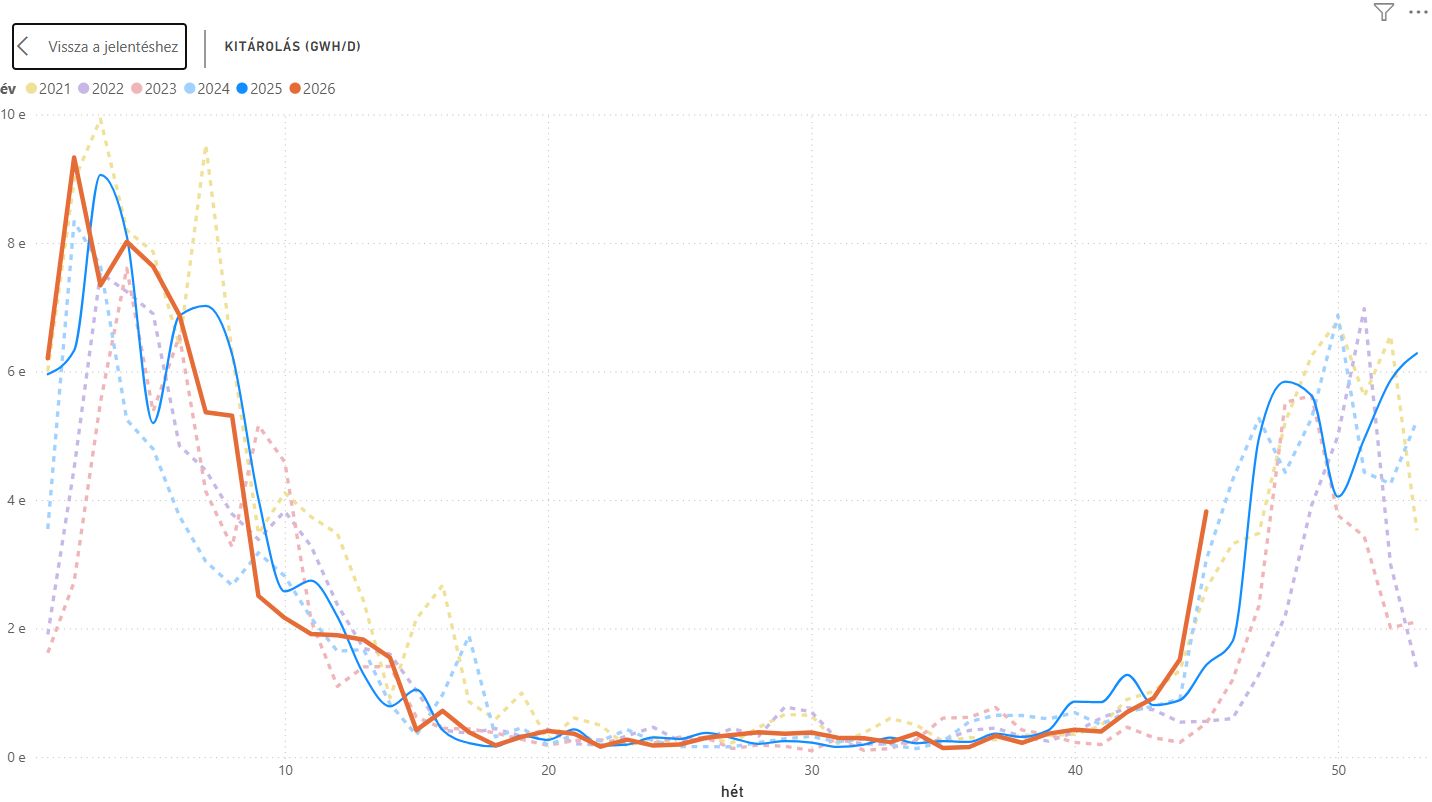
Norwegian gas flow nominations reached 330.7 mcm on Friday, up 2% week-on-week, providing a relatively stable supply backdrop for now.
Although short-term price pressure remains to the downside, some market participants do not rule out TTF prices returning to around EUR 100/MWh within the next month.
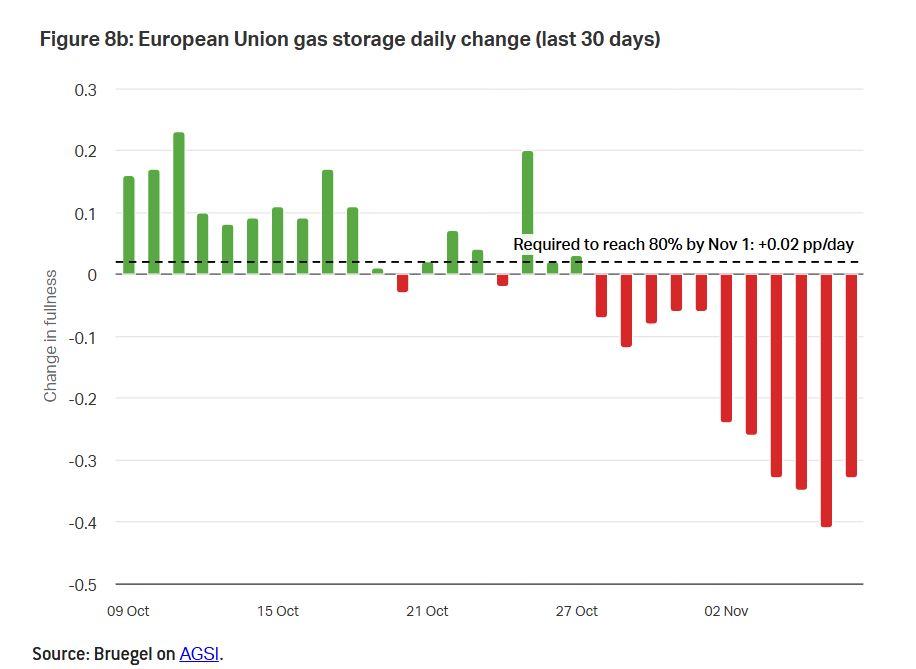
Geopolitics – The Strait of Hormuz remains a critical risk factor
Trump is scheduled to meet Qatar’s Prime Minister on Monday, following the latter’s visit to Tehran last week. Diplomatic mediation efforts have intensified, but US and Gulf officials remain sceptical about the prospects of an imminent agreement.
Iran has linked an end to the war to the lifting of the blockade on its ports, the easing of certain sanctions and a halt to bombing, offering in return to end its blockade of Hormuz. Washington has rejected these conditions, and no diplomatic breakthrough appears imminent.
Attacks on tanker vessels increased significantly in Oct and have continued at elevated levels in Nov.
A building belonging to Saudi state oil company Aramco in Riyadh was also hit. These developments highlight the continued risk of further regional escalation.
Market outlook
The current TTF correction does not yet signal a fundamental improvement in the European gas market. Falling oil prices may exert downward pressure on gas prices in the short term, but storage levels of just 73%, early withdrawals, winter weather exposure and uncertainty surrounding Norwegian supplies continue to pose significant upside risks.
Geopolitical developments remain particularly important: the lack of a diplomatic breakthrough could keep the risk premium in LNG supply elevated
Source:Montel News Bruegel – Improving economic policy
Analysis written by: Tóth Eszter Lilla
09.11.2026